Vellora Heights’ advertised 30-month payment period should be treated as an invitation to request a full written instalment schedule not as a substitute for reviewing contract terms. The developer’s brief mentions a two-and-a-half-year plan and preliminary starting prices, but no deposit amount, monthly schedule or approved instalment formula is provided.
1. What is the actual deposit?
Ask whether an initial reservation fee is separate from the deposit, when it is credited to the purchase price, and what documents are signed at each stage. A deposit can influence the size and timing of later instalments, so it should appear in the unit-specific written quotation. Do not assume that another Gazebo development’s reservation terms also govern Vellora Heights. The project brief confirms the duration, not an approved deposit percentage. Before paying, verify the receiving legal entity, official account, receipt procedure and any conditions for cancellation or return of the reservation money.
2. Are instalments monthly or tied to building progress?
Thirty months describes a period, not the frequency of payments. A schedule might be monthly, quarterly, milestone-based or a combination; only the written contract can establish Vellora’s terms. Ask for a table giving due dates, amounts, cumulative paid value and construction-related conditions where relevant. Also clarify what happens if construction progresses more slowly than anticipated. Your obligations should be explained independently of any sales-team verbal summary. Keep a cash-flow buffer rather than arranging household finances around the assumption that every payment can be postponed without consequence.
3. How should I interpret the starting prices?
The brief lists US$55,000 as the preliminary starting price for two-bedroom units and US$85,000 for three-bedroom units. Those are negotiable starting asking prices, subject to change. They do not state the price for a specific floor, view or unit size. Obtain a quote showing the chosen unit, effective price, currency and quote expiry. The final cost can also depend on transaction expenses, legal fees and optional or separately charged items. If the agreement fixes an exchange rate, request that provision in writing rather than assuming the Kenyan-shilling equivalent will remain constant.
4. What could a simple illustration look like?
Consider a purely hypothetical two-bedroom example at US$55,000 with a 20% deposit. That would mean an initial US$11,000 and a remaining US$44,000. If—and only if—the balance were divided evenly over 30 months, the arithmetic would be about US$1,467 monthly before any other charges. This is not a Vellora offer and must not be used as a quote. Different deposit amounts, milestone dates or charges produce different instalments. A serious buyer should use the developer’s approved schedule and test it against income, emergency savings and other household obligations.
5. What happens if the buyer or project misses a deadline?
Review the agreement for late-payment penalties, grace periods, notices, default procedures and any right to reschedule. Equally important are provisions addressing changes to project completion, material specifications, unit area and handover. Understand when cancellation is allowed, what deductions can apply and how any refund would be calculated and paid. A sales assurance that “the plan is flexible” needs contractual support if flexibility matters to your decision. If the clauses are unclear, ask your own advocate to interpret them before signing. The State Department for Lands also recommends official land search as part of property due diligence.
6. What else will I need money for?
A purchase budget should include more than instalments. Ask about stamp duty where applicable, advocate’s fees, transfer or registration expenses, utility connection charges, parking, service-charge deposits, insurance and any recurring management costs. Avoid assuming these are all included in the quoted starting price. Assess whether the property will be owner-occupied or rented, because vacancy and operating expenses can change the investment’s cash demands. For purchasers earning in a different currency, test an unfavorable exchange-rate scenario. An affordable monthly figure is not proof that the overall commitment is affordable.
Payment-plan checklist to request
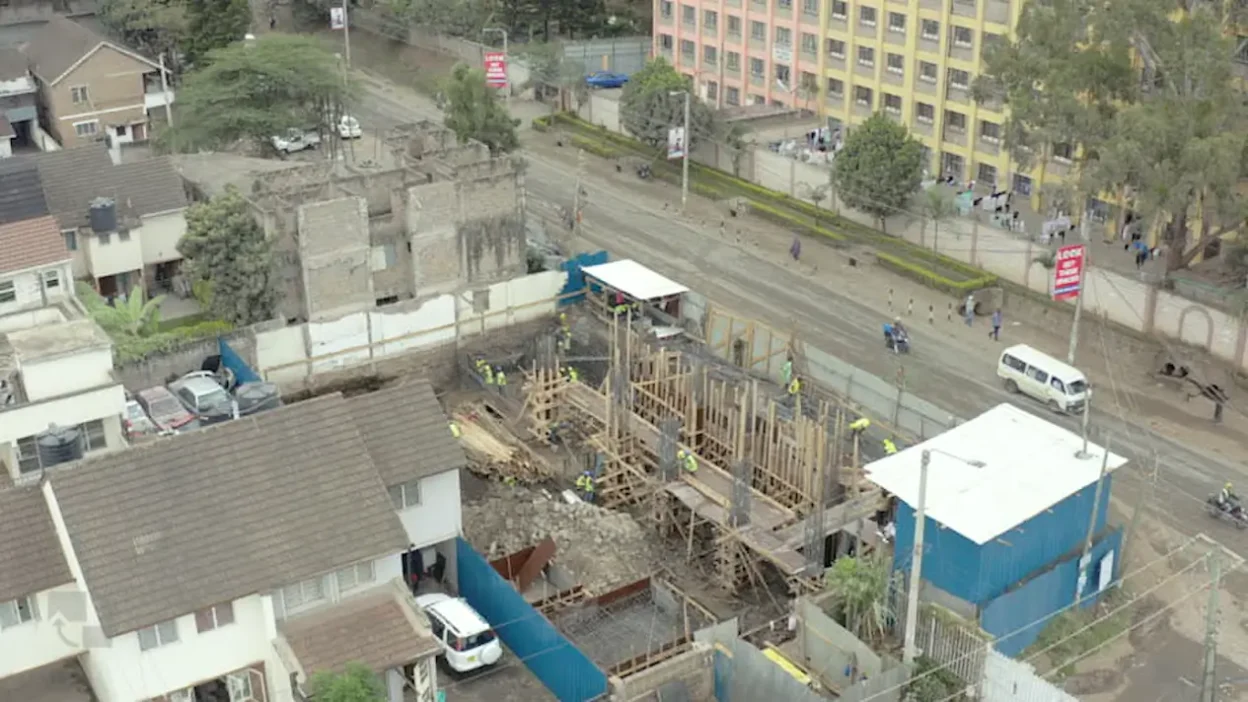
Ask Gazebo Homes for: a dated unit-specific quote, deposit figure, due-date schedule, official payment instructions, refund/default provisions, construction milestones, estimated handover date and full list of known additional costs. Keep the document alongside the approved unit plan and draft sale agreement. Vellora’s source brief reports groundbreaking completed, but it does not establish the time remaining until completion; do not confuse a 30-month payment window with a guaranteed handover schedule.
Common questions
Is the plan interest-free? The supplied Vellora brief does not state this. Ask the developer to confirm any financing or administrative charges in writing.
Are prices guaranteed for buyers who inquire early? No guaranteed price lock is established in the source. Starting prices are preliminary and subject to change.
Can diaspora buyers use the plan? Contact the sales team about permitted payment methods and documentary requirements. Do not assume cross-border transaction terms.
Request the official payment schedule
Call or WhatsApp +254 748 000 020, or contact Gazebo Homes Ltd. An approved written instalment schedule—and independent legal review—should come before a reservation decision.
Sources and verification notes
- State Department for Lands — public source checked on 3 November 2026; publisher claims are not independently audited.
- Gazebo Homes Ltd — public source checked on 3 November 2026; publisher claims are not independently audited.
- Developer-supplied source: About Vellora Heights.docx (Gazebo Homes Ltd project briefing; preliminary unit mix, price and payment-period figures; latest terms require confirmation).